
FY2027 Outlook: Resilient economy signals upside in undervalued markets
Strong macro fundamentals and low inflation place India in a “Goldilocks” zone. Valuations near long-term averages signal potential for above-average market returns.
Strong macro fundamentals and low inflation place India in a “Goldilocks” zone. Valuations near long-term averages signal potential for above-average market returns.
A temporary ceasefire may cool the recent surge in chemical prices, but supply disruptions continue to keep costs elevated.
The number of transactions rose to 60 in FY26, the highest in seven years and up sharply from 41 deals in FY25. Average deal size, at USD 71 million, was the lowest in the same period.
The Reserve Bank of India’s decision to hold rates signals a cautious, hawkish undertone amid global uncertainties, even as it maintains policy stability.
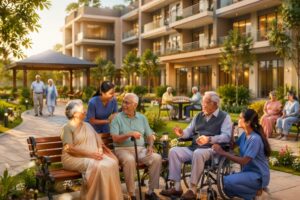
Assuming 3% penetration over the next 10 years and spend of ~Rs 40,000 per senior per month by 2036, the specialised senior care market could be ~USD 35 billion per annum.
Escalating tensions in West Asia are pushing up energy costs and widening macro risks for India. From slower growth to higher inflation, the spillover effects could shape FY27 outlook.
After a soft start, India’s 10Y yield turned sticky in H2FY26 amid rising supply concerns and global geopolitical tensions. Oil shocks and volatile capital flows have added to upside risks, keeping yields elevated.
The Sensex declined by around 7%, led largely by decline in real estate, IT and FMCG stocks. However, this trend can reverse soon as on a fundamental level, these sectors remain robust.
The RBI is expected to hold the policy repo rate unchanged at 5.25% and keep the stance as neutral.
At the city level, Delhi NCR drove over one-fourth of the total quarterly investments, attracting USD 0.4 billion, followed by Bengaluru with inflows of USD 0.3 billion.