
Buying a home? The real cost of a rate hike goes beyond your EMI
A rise in interest rates can push up EMIs or stretch loan tenures, adding to the cost of homeownership. Here’s how new buyers can weigh their options and manage the risk.
As interest rates move through cycles, the smartest home loan may not always be the one with the lowest headline rate today. (Image: Freepik)
Buying a home is expensive enough. There is the down payment to arrange, stamp duty and registration to pay, and then the cost of getting the house ready to move into. For many families, the first few years after buying a home are a time of tight budgets and careful spending.
Now, rising interest rates could make things a little harder.
The Reserve Bank of India has raised the repo rate by 25 basis points to 5.50% and shifted its policy stance to calibrated tightening. For home loan borrowers, this brings an uncomfortable question back into focus: how much more will the loan cost if interest rates continue to rise?
Most borrowers worry about their EMIs going up. But there is another cost that can slip under the radar. If the EMI remains unchanged after an interest rate hike, the bank may extend the loan tenure instead. The monthly payment stays the same, but the borrower could end up paying interest for several more years.
That can make a considerable difference over the life of a home loan, particularly when the repayment period is already 20 or 30 years.
Floating-rate loans are popular partly because their initial interest rates can be attractive. But the rate is not set in stone. When interest rates change, borrowers may have to pay a higher EMI or stay with their existing EMI and take longer to repay the loan.
Neither option is particularly comfortable. A higher EMI means finding more money every month, while a longer tenure means staying in debt for longer and potentially paying more interest overall.
For someone who has just bought a home, this can be especially difficult. The household budget may already be stretched by the purchase, and there may be other expenses to deal with, from furnishing the house to rebuilding savings depleted by the down payment.
The latest rate hike also serves as a reminder that interest rates do not remain at the same level throughout a long-term loan. The repo rate is still 100 basis points below the 6.50% level seen in the previous rate cycle. A homebuyer who takes a loan today needs to consider not just the EMI at the time of borrowing, but also how comfortably the household could manage if rates rise further.
Can homebuyers get some breathing room?
For new borrowers, knowing how much they will have to pay each month can make financial planning easier. This is particularly true in the early years of homeownership, when expenses tend to pile up and there may be little room for an unexpected increase in the EMI.
Kotak Mahindra Bank’s Hybrid Home Loan is designed to offer some certainty during this period. Eligible customers can choose to keep their interest rate fixed for 39, 52 or 65 months. The pricing is comparable to the bank’s floating-rate home loan, with no separate premium for opting for the hybrid structure.
During the selected period, the interest rate and EMI remain unchanged, even if the repo rate goes up. Once that period ends, the loan moves to a floating rate linked to the repo rate, along with a predefined spread disclosed when the loan is sanctioned.
For a new homebuyer, the benefit is fairly straightforward: there is less uncertainty about the monthly repayment for the first few years. That can make it easier to plan household expenses without worrying about every change in interest rates.
However, the protection does not last for the entire loan. Borrowers should check what rate will apply once the fixed period ends and understand how a subsequent rate increase could affect their EMI, repayment period and total interest bill.
After all, the real cost of a home loan is not just the amount that leaves your bank account every month. It is also the amount you end up paying the bank by the time the loan is finally repaid.
Illustrative EMI Comparison: Impact of a 100 bps Repo Rate Increase Over 65 Months
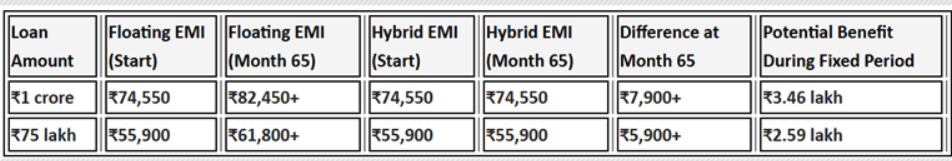
Illustration for explanatory purposes only. Assumes home loans of ₹1 crore and ₹75 lakh with a 25-year tenure, a fixed interest rate of 7.60%, a 65-month fixed-rate period and a cumulative 100 basis point increase in the Repo Rate from 5.50% to 6.50% during that period. A Repo Rate of 6.50% was the highest level seen during the previous rate cycle. Actual outcomes will vary depending on loan amount, tenure, benchmark movements, customer profile and applicable terms and conditions.
Nakul Saxena, Business Head – Mortgages, Kotak Mahindra Bank, said: “The latest policy decision is a reminder that interest rates move through cycles. The first few years after buying a home are often the most financially demanding for borrowers as they are rebuilding savings while managing multiple household commitments alongside a new EMI. In such an environment, the key question is not whether rates will rise or fall, but how much uncertainty a household budget can comfortably absorb.”
He added: “Many borrowers focus on securing the lowest rate at the time of loan sanction. However, they should also consider what happens if interest rates rise over the next few years. For customers who value repayment certainty, a hybrid home loan can provide a defined period of protection from both EMI increases and tenure extensions arising from Repo Rate hikes.”
As interest rates move through cycles, the smartest home loan may not always be the one with the lowest headline rate today. It may be the one that best balances affordability, flexibility, certainty and long-term cost.